Investment Planning

Q3 2026 Investment Commentary

Center for Financial Planning market insights and commentary for the third quarter of 2026.insights

The Center Contributed by: Center Investment Department

Print Friendly and PDF

The third quarter came and went in what felt like the blink of an eye.  It brought with it important reminders that markets rarely move in a straight line. When looking “under the hood” of the market, performance was very uneven. During the quarter, domestic U.S. large-cap equities ended up around 2% (S&P 500 Index) while U.S. small-cap equities retreated over 7% (Russell 2000 Index).  Overseas markets were mixed with developed international investments up about 0.5% (MSCI ACWI Ex USA Index) while emerging markets were down almost 0.4% (MSCI EM Index). Energy stocks were among the strongest performers as geopolitical tensions in the Middle East pushed oil prices higher, while portions of the technology and broader growth complex experienced bouts of volatility. At the same time, rising interest rates created a challenging environment for fixed income as bonds were down about 3.5% for the quarter, illustrating once again the importance of diversification across asset classes and investment styles.

As we turn our attention to fall, the election is grabbing much of our attention now with midterm elections on November 3rd. All 435 seats in the U.S. House of Representatives and 35 U.S. Senate seats will be decided, creating the potential for a change in congressional control. With change comes volatility. Yet history offers a useful reminder that elections tend to create more uncertainty in the headlines than they do lasting changes in market direction. Please join us for our upcoming webinar, Elections & Markets, where we discuss the unique challenges that elections pose to equity and bond markets and the investing fundamentals that are so important to follow during these times.

Iran, Inflation and Interest Rates

The Federal Reserve returned to center stage in September. They raised the federal funds target range by 25 basis points to 3.75%-4.00%, its first interest rate increase since 2023, as policymakers try to combat inflation stemming from increased energy prices. The Fed is projecting core PCE inflation of 3.4% for the year while it currently stands at 3%. Remember, the Fed is still targeting 2.0% inflation over the long term.  Higher inflation can be directly tied to the ongoing conflict in Iran.  The June cease-fire agreement with Iran quickly fell apart in early July causing continued restrictions on the movement of oil out of the region. Now with strategic national reserves dipping down to all-time lows, the U.S. is running out of levers to pull to stem the rise in gas and diesel prices. The quarter ended with no meaningful agreement in place. The price of oil, and therefore gas, will continue to remain volatile as talks continue.

Volatility in the Bond Market

Speaking of raising rates, it isn’t just the Fed Funds rate being increased due to sticky inflation. Bond rates across the yield curve have been increasing in response to higher inflation, better-than-expected economic data, strong stock earnings, and increased borrowing from the world’s largest companies looking to raise capital for the ongoing AI buildout. There have been a lot of competing forces causing investors to sell bonds or at least demand a higher interest rate in order to hold those bonds. The headlines have been loud, but context always matters – the Bloomberg U.S. Aggregate Bond Index is down 2.9% year-to-date. Rising yields can be worrisome to investors, but volatility in any asset class is normal, and with the “Agg” index yielding near 5%, much of this price movement is being offset by the current yield. For more details on this topic, see our full post: “What’s Going On With the Bond Market?”

AI

It seems like you can’t separate the market and AI lately; the two topics go hand in hand as the world’s largest tech companies continue to drive the market forward with the strongest earnings gains and, in many cases, the best stock performance so far for the year. Semiconductors and energy are the two top-performing sectors YTD driven by the AI trend, and of course higher energy prices from the Iran conflict. From roaring stock prices to literal doomsday headlines, AI is giving us a little bit of everything this quarter. Large tech companies, federal and local governments, investors, and users of the technology are figuring out what and how exactly this new technology will be utilized going forward and what it’s impact to our economy will be.

Elections and Markets

It’s rare that, in an election year, many of the headlines surround international conflicts rather than domestic issues, but that is where we find ourselves.  Historically, midterm elections are difficult for the president’s party, and this year is unlikely to be an exception as the president’s approval rating has been steadily declining and is near historic lows.
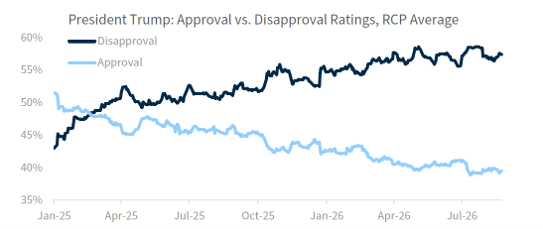
Chart that illustrates President Trump's approval rating has been steadily declining and is near historic lows.

Source: Raymond James and RealClearPolitics. Data as of 9/14/2026

While the Senate could go either way, it is likely that the House will flip to Democratic control.  Michigan is considered one of these crucial battleground states for our Senate race.  Republicans have been in full control over the past two years, albeit by a very small margin.  Markets have historically responded well to divided government, as gridlock can reduce the likelihood of significant policy changes.  That said, the past two years under unified government have also produced strong market returns.  It is always important to zoom out and remember that politics should never dictate our investment strategy.  It is important to stay focused on investing fundamentals at this time, such as rebalancing.

What Are We Doing Now? Rebalancing & Tax-Aware Portfolio Management

Periods of market volatility can create an opportunity to reinforce disciplined portfolio management through rebalancing. As markets move, asset allocations often drift from their intended targets, potentially increasing risk or reducing exposure to areas that may offer future long-term value. Regular rebalancing is an integral part of our ongoing portfolio monitoring process. It helps bring portfolios back in line with strategic objectives by trimming positions that have outperformed and adding to areas that have lagged. While this approach may feel counterintuitive during times of uncertainty, it encourages investors to remain focused on long-term asset allocation rather than short-term market fluctuations.

Market volatility can also create favorable conditions for tax-loss harvesting, a strategy designed to enhance after-tax returns. Taxes can represent a meaningful drag on long-term investment performance, making tax management an important consideration within the investment process. When appropriate, we may realize losses in select investments to offset current or future capital gains while maintaining strategic market exposure through carefully selected replacement holdings. Although tax considerations should not drive investment decisions on their own, thoughtful tax-loss harvesting can add value and improve tax efficiency during periods of market dislocation. For readers interested in a deeper understanding of how tax-loss harvesting works and its potential benefits, we invite you to read our blog on the topic.

Periods of heightened market uncertainty often create discomfort, but they can also create opportunities. During these periods, our focus remains on adhering to the disciplined investment process established for each of you that can go hand in hand with responding to opportunities created by short-term market movements. Rebalancing and tax-aware portfolio management are two practical ways we seek to add value, helping maintain strategic portfolio alignment while enhancing tax efficiency when appropriate. Together, these strategies reinforce our long-term approach to investment management and our commitment to helping you navigate market volatility with confidence and discipline.

As we enter the final quarter of the year, investors continue to face a landscape shaped by geopolitical tensions, evolving monetary policy, shifting market leadership, and an approaching election. While these events may drive short-term volatility and dominate headlines, history reminds us that long-term investment success is rarely determined by any single news cycle or market event. Instead, disciplined decision-making, diversification, and adherence to a thoughtfully constructed investment plan remain among the most reliable drivers of positive outcomes over time. At The Center, we remain committed to helping clients navigate uncertainty with perspective and purpose, utilizing tools such as rebalancing and tax-aware portfolio management while staying focused on what matters most: helping you achieve your long-term financial goals with confidence.

Angela Palacios, CFP®, AIF®, is a partner and Director of Investments at Center for Financial Planning, Inc.® She chairs The Center Investment Committee and pens a quarterly Investment Commentary.

Nicholas Boguth, CFA®, CFP® is a Senior Portfolio Manager and Associate Financial Planner at Center for Financial Planning, Inc.® He performs investment research and assists with the management of client portfolios.

Mallory Hunt is a Portfolio Administrator at Center for Financial Planning, Inc.® She holds her Series 7, 63 and 65 Securities Licenses along with her Life, Accident & Health and Variable Annuities licenses.

Opinions expressed are those of the author/speaker and are not necessarily those of Raymond James. All opinions are as of this date and are subject to change without notice. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Past performance may not be indicative of future results. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Every investor’s situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. The forgoing is not a recommendation to buy or sell any individual security or any combination of securities. The indexes mentioned are unmanaged and cannot be invested into directly. Past performance is no guarantee of future results.
What's Going On With the Bond Market?

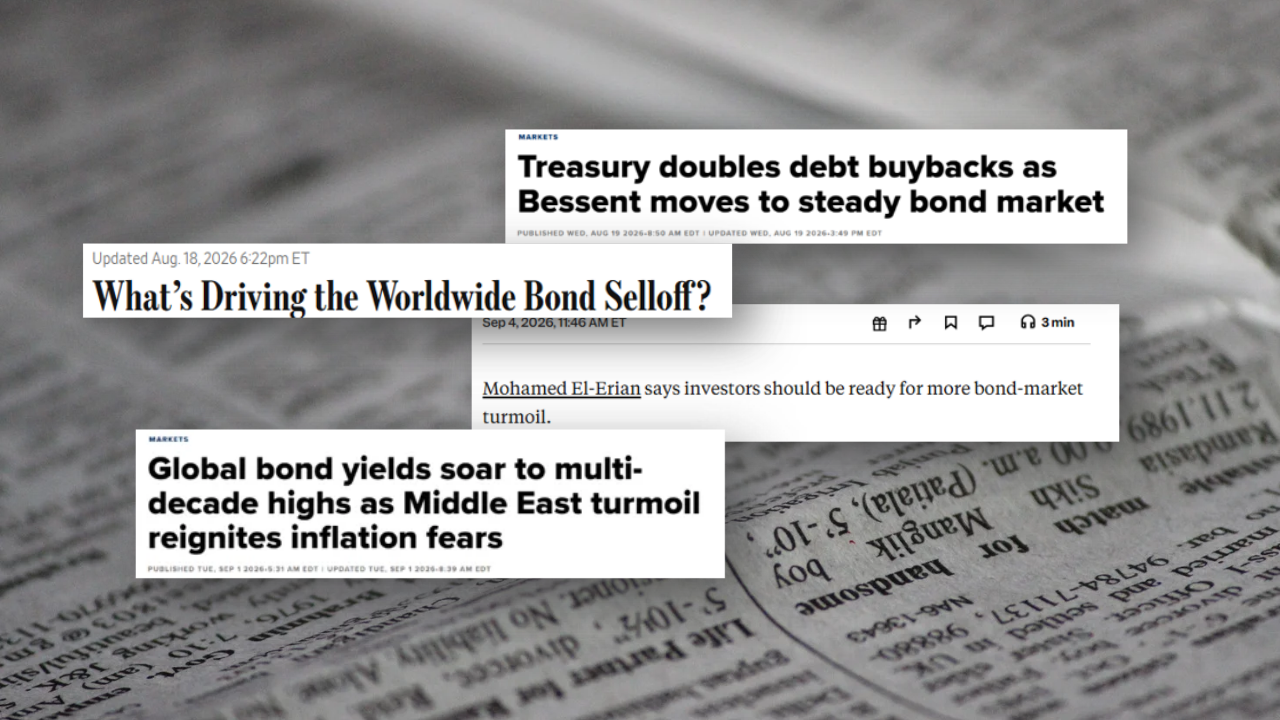
Financial news headlines highlighting bond market volatility, rising Treasury yields, inflation concerns, and global fixed-income market uncertainty.
Print Friendly and PDF

Many things are in the news! But the takeaway might be the exact opposite as it may seem from the headlines.

Selloff, turmoil, government intervention, yields soaring – this could lead investors to feel uneasy about their bond holdings and want to act. Everyone’s situation is different, so I am not suggesting a one-size-fits-all approach, but here are some facts and context to help us make some informed decisions rather than panic-selling from some scary headlines.

First off, let’s start with the fact that the U.S. Bond Index (Bloomberg U.S. Agg Bond TR) is down a whopping -0.31% through 8/31/26…sometimes context is important.

Secondly, let’s take a step back and remind ourselves why we own bonds in the first place…

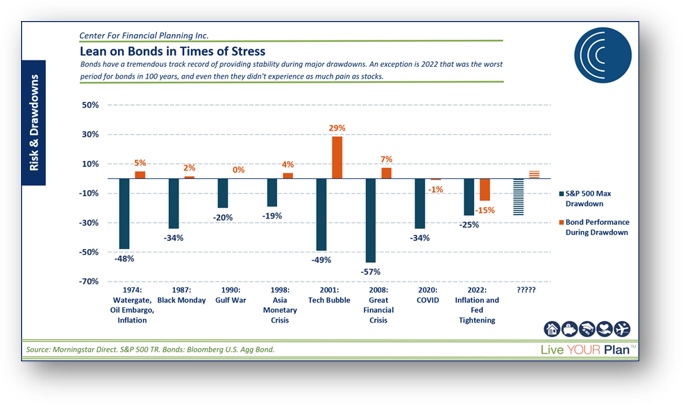
Bar chart comparing stock market drawdowns and bond performance during major financial crises, highlighting the diversification benefits of bonds during market volatility.

…historically, bonds can provide stability when needed. This holds true MOST of the time. Look at 7 of these 8 periods above. In the market’s hardest moments when stocks fell the most, bonds held their value or even provided positive performance.

The reason investors are paying extra close attention to bonds right now is because they failed us last time, and investors are worried they are going to fail us again. 2022 was a rare time in history when both stocks AND bonds fell at the same time. This happened because of a rare combination of very low starting yields and a VERY aggressive Fed tightening cycle to combat inflation coming out of the Covid era.

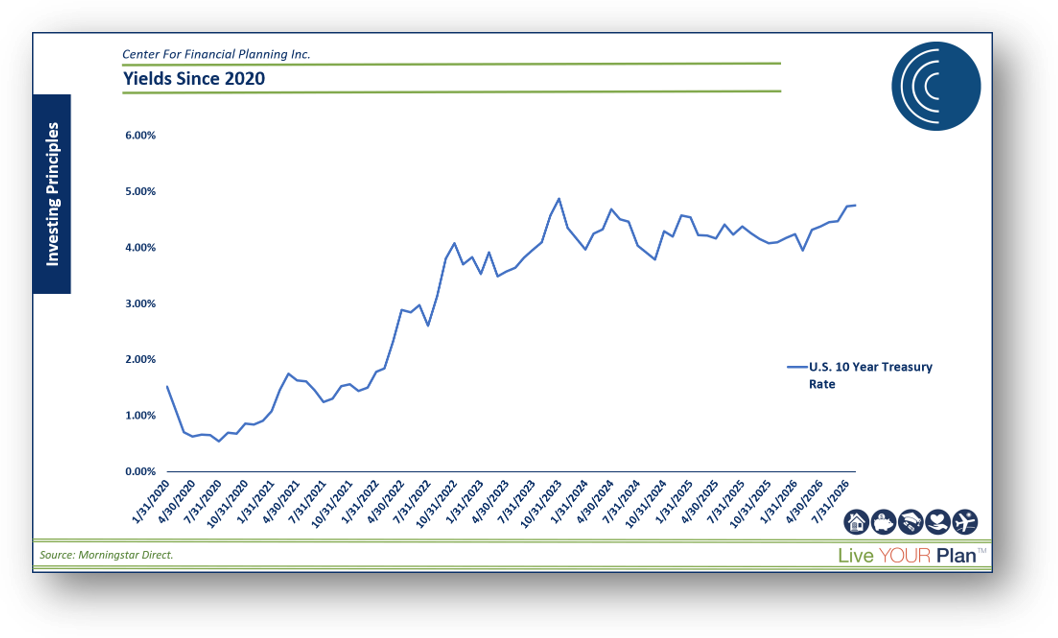
The important thing to remember is today is VERY different than 2022. In 2022, bonds were yielding near ~2%! Today, closer to 5%.  Generally speaking, there is much more upside to yields (and downside to bond prices) when starting yields are so low.

Line chart showing U.S. 10-Year Treasury yields rising from 2020 through 2026, illustrating interest rate trends and bond market performance.

How is this conflict with Iran going to end? Are tariffs here to stay? What is going to happen with U.S. tax revenue and government spending over the next 10 years? How is the A.I. productivity story going to play out? Where is the price of oil going from here? Does U.S. GDP grow at 0% or 5% in the coming years? Does inflation trend above 3% or come back down to the Fed’s 2% target? The uncomfortable truth is nobody knows what happens next. The future hasn’t been written yet. The comforting part is that this volatility and uncertainty is offering some compelling investment opportunities for investors to take advantage of.

The bond market is adjusting to all these variables on the fly, which is why it is demanding headlines. Rates could certainly move higher with negative news on any of those topics from above in the short-term, but for most of our clients we are not ONLY planning for the next 12 months. We are likely planning for the next 12 YEARS, and most of the time even further out than that.

Diversification remains a core investment belief for our firm, and every investor is different in their risk tolerance, time horizon, and goals – but bonds offering 4 to 5% on the short end of the yield curve and 5 to 6% on the long end of the yield curve can be a powerful tool in the toolkit when it comes to a retirement plan. Another thing to consider is that U.S. bonds are not the only bonds out there on the market that an investor can choose from. If you fear U.S. rates are going higher, but have a more positive outlook on rates elsewhere, there are many ways to express that view in your portfolio. Or if you want to truly explore other investment opportunities that could help guard against rising inflation, there are other asset classes to look into as well!

Above all else, a commitment to your financial plan is imperative. When we build a financial plan, we consider many different outcomes from bond volatility to market drawdowns to different paths for inflation going forward. Diversification and a commitment to the financial planning process help guide us to build resilient financial plans for many different market environments, and for now, we are here to help answer any questions about how these headlines might affect your portfolio and your financial plan today.

Nicholas Boguth, CFA®, CFP® is a Senior Portfolio Manager and Associate Financial Planner at Center for Financial Planning, Inc.® He performs investment research and assists with the management of client portfolios.

Opinions expressed are those of the author/speaker and are not necessarily those of Raymond James. All opinions are as of this date and are subject to change without notice. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Past performance may not be indicative of future results. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Every investor’s situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. The forgoing is not a recommendation to buy or sell any individual security or any combination of securities. The indexes mentioned are unmanaged and cannot be invested into directly. Past performance is no guarantee of future results.
Retiring with Company Stock? Don't Overlook This Potential Tax Opportunity

A retiree reviews company stock holdings as part of a tax-efficient retirement income strategy using Net Unrealized Appreciation (NUA).

Logan Dimitrie Contributed by: Logan Dimitrie, CFP®

Print Friendly and PDF

Many employees spend decades building their retirement savings through company-sponsored plans and employee stock ownership programs (ESOP). As retirement approaches, one of the most important questions you should be asking: How can I withdraw these assets in the most tax-efficient way possible?

One strategy that often goes overlooked is called Net Unrealized Appreciation (NUA). While it isn't right for everyone, it may provide tax advantages when used in the right situation. Combined with thoughtful Social Security timing, it may help improve retirement outcomes and mitigate future tax burdens.

What Is NUA?

NUA refers to the increase in value of employer stock held inside a qualified retirement plan such as an ESOP, 401(k), or profit-sharing plan.

Normally, when pre-tax retirement assets are withdrawn, the entire distribution is taxed as ordinary income. However, employer stock may qualify for special tax treatment under NUA rules.

Instead of transferring the company stock into an IRA, the stock is distributed to a taxable brokerage account. The original cost basis of the shares is taxed as ordinary income at the time of distribution, but the appreciation above that cost basis receives long-term capital gains treatment when the stock is eventually sold.

Since long-term capital gains rates are often lower than ordinary income tax rates, the result can be substantial tax savings.

Example

Assume an employee has company stock in an ESOP valued at $500,000.

The original cost basis of the shares is $100,000.

  • Cost basis: $100,000

  • Appreciation (NUA): $400,000

  • Total value: $500,000

If the entire account were transferred to an IRA and later withdrawn, the full $500,000 could eventually be taxed as ordinary income.

Using an NUA strategy, only the $100,000 cost basis is taxed as ordinary income when distributed. The remaining $400,000 may qualify for long-term capital gains treatment when sold in the future.

Depending on the client's tax bracket, the savings can be meaningful.

This is a hypothetical example and is not intended to reflect actual performance.  Future performance cannot be guaranteed and investment yields will fluctuate with market conditions.  Investments involve risk and you may incur a profit or loss.

Why Social Security Timing Can Matter

One challenge with NUA planning is that the cost basis becomes taxable income in the year of the distribution.

This is where Social Security planning may become part of the discussion.

For those who can afford to delay claiming benefits, postponing Social Security can help keep taxable income lower during the NUA year. This may create an opportunity to recognize the cost basis at a more favorable tax rate.

Delaying Social Security typically increases future benefit payments. For many folks, benefits grow approximately 8% per year beyond full retirement age until age 70.

This could be incredibly beneficial due to:

  1. Lower taxable income during the NUA transaction year

  2. Potentially higher future Social Security benefits

  3. Favorable capital gains treatment on appreciated company stock

Another Potential Benefit: Lower Future RMDs

Folks with significant balances in their pre-tax 401(k) or Traditional IRA are concerned about Required Minimum Distributions (RMDs).

When employer stock is removed from a retirement account through an NUA transaction, those assets are no longer held inside the tax-deferred account. As a result, the amount subject to future RMD calculations may be reduced.

A smaller IRA balance can potentially lead to:

  • Lower future RMDs

  • Greater control over taxable income in retirement

  • Reduced exposure to Medicare IRMAA surcharges

  • More flexibility with Roth conversion strategies

  • Potential tax savings for heirs

For folks with large balances in pre-tax accounts, this can be an important benefit.

When is NUA treatment worth it?

NUA is worth considering when:

  • You have highly appreciated company stock inside an ESOP or 401(k).

  • The stock's cost basis is significantly lower than its current market value.

  • You expect to be in a moderate or higher tax bracket during retirement.

  • You have flexibility in when to claim Social Security.

  • You want to reduce future RMD exposure.

It doesn’t always make sense.

Like most planning strategies, NUA isn't always the right answer.

It may not be beneficial when:

  • The stock has little appreciation.

  • The cost basis is already relatively high.

  • You expect to be in a significantly lower tax bracket later.

  • Concentration risk in company stock is a concern.

  • Cash flow needs require immediate liquidation.

This is why careful tax analysis is critical before making any decisions.

Retirement Planning Is More Than Investments

One of the most common mistakes we see is focusing exclusively on investment performance while overlooking tax strategy.

The most effective retirement plans coordinate multiple moving pieces, including:

  • Social Security timing

  • Retirement account distributions

  • Tax planning

  • Employer stock decisions

  • Roth conversion opportunities

  • Estate planning considerations

Often, the difference between a good retirement outcome and a great one comes from how these pieces work together.

Final Thoughts

If you're preparing to retire and have company stock in an ESOP or employer retirement plan, NUA may be something to consider. When combined with thoughtful Social Security planning and long-term tax management, it has the potential to improve after-tax retirement income and reduce future tax liability.

The key is recognizing that every situation is unique. Before making elections involving company stock, retirement plans, or Social Security, work with a qualified financial and tax professional who can evaluate the strategy in the context of your overall retirement plan.

Author's Note

At the Center for Financial Planning, we frequently analyze retirement income strategies that go beyond traditional investment management. For employees retiring with ESOP or company stock benefits, evaluating NUA treatment alongside Social Security timing, tax projections, and future RMD planning can uncover opportunities that might otherwise be missed. Even if NUA ultimately isn't the right fit, it should be part of the conversation.

Logan Dimitrie is a Client Service Associate at Center for Financial Planning, Inc.®. He combines his passion for supporting seniors, advisors, and team members with past retirement account experience to provide exceptional service.

Any opinions are those of Logan Dimitrie and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice. Raymond James and its advisors do not offer tax advice. You should discuss any tax matters with the appropriate professional. Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Be sure to consider all of your available options and the applicable fees and features of each option before moving your retirement assets.

Diversification: Timeless and Yet Misunderstood

Shopping cart full of different investment products to represent diversification

Tim Wyman Contributed by: Timothy Wyman, CFP®, JD

Print Friendly and PDF

As I was thinking about this topic, I revisited some excellent Morningstar research on portfolio diversification and investor behavior, which helped inspire a few of the ideas discussed below.

Have you ever noticed that the investments getting the most attention are almost always the ones investors wish they owned more of?

One year it's technology stocks. Another year it's artificial intelligence. Sometimes it's real estate, gold, international markets, or whatever happens to be leading the headlines. The temptation is understandable. When one area of the market is soaring, it can feel like the obvious place to invest.

The problem is that today's winners are rarely obvious in advance.

That's one of the reasons diversification remains one of the most important, and often most misunderstood, principles in investing. It won't always produce the highest return in any given year. In fact, there will be times when diversification feels frustrating because part of your portfolio is inevitably lagging behind. But over the long run, a thoughtfully diversified portfolio can help investors stay disciplined, manage risk, and improve the odds of achieving the goals that matter most.

One of the interesting things about investing is that some of the best decisions rarely feel like the most exciting ones.

Diversification is a perfect example.

Most people have heard the phrase, "Don't put all your eggs in one basket." While that's a good starting point, true diversification is about much more than simply owning a bunch of different investments.

In fact, it's possible to own several mutual funds or ETFs and still not be very diversified if they all behave similarly or own many of the same companies. Diversification isn't about the number of investments you own. It's about owning investments that respond differently to changing economic and market conditions.          

Said another way, effective diversification is really about correlation. Assets don't need to rise and fall in opposite directions all the time, but they shouldn't all react exactly the same way to every market event. The greatest diversification benefits often come from owning investments with lower or even negative correlations, meaning some parts of the portfolio may hold their value or even appreciate when other areas are under pressure. Over time, that interaction can help smooth returns and reduce the impact of major market declines.

The challenge is that diversification can feel frustrating at times.

A properly diversified portfolio will almost always have something in it that isn't performing particularly well. When large technology stocks are surging, bonds may seem unnecessary. When U.S. stocks are leading the way, international investments may appear to be lagging behind. It's natural to wonder why we own certain positions when something else is grabbing all the headlines.

Ironically, that's often a sign that diversification is doing exactly what it's supposed to do.

One of the conversations we frequently have with clients is the difference between chasing the highest possible return and building a portfolio designed to help achieve their most important goals. Most families aren't investing to win a performance contest. They're investing to retire comfortably, support children and grandchildren, fund charitable causes, preserve their purchasing power, and create long-term financial security.

In nearly 30 years of working with families, I've rarely seen a financial plan fail because a client didn't own enough of the year's best-performing investment. More often, problems occur when investors take concentrated risks that don't work out as expected.

A portfolio that experiences fewer extreme outcomes may be more likely to help achieve those goals than one concentrated in a single asset class, sector, or investment theme. For example, a 50% loss requires a 100% return just to get back to your starting point. A 15% decline, on the other hand, requires only about a 17.6% gain to recover. This is one of the reasons we spend so much time managing downside risk. While investors naturally focus on returns, avoiding large losses can have an even greater impact on long-term wealth accumulation. Our objective isn't to eliminate volatility, which is impossible, but rather to help clients avoid the type of losses that can permanently derail a financial plan.

Recent years have provided plenty of reminders of why diversification matters. Different asset classes have taken turns leading the market. There have been periods when U.S. stocks dominated, periods when international markets outperformed, and periods when bonds, real estate, commodities, or gold provided meaningful benefits. The problem is that very few people consistently predict which asset class will be next in line.

Diversification acknowledges that reality. Instead of trying to guess the next winner, it recognizes that nobody knows with certainty what the next few years will bring.

Of course, diversification doesn't eliminate risk, and it certainly doesn't guarantee positive returns. Markets will always experience periods of volatility. However, diversification remains one of the most effective tools investors have for balancing growth opportunities with prudent risk management.

In the end, successful investing is rarely about finding the one investment that outperforms everything else. More often, it's about building a collection of investments that can work together through a variety of market environments.

The best portfolios are not always the ones that generate the highest return in any single year. More often, they're the ones that help investors stay disciplined, remain invested during difficult periods, and ultimately achieve the goals that matter most.

And that's really what diversification is all about.

Timothy Wyman, CFP®, JD, is the Managing Partner and CERTIFIED FINANCIAL PLANNER™ professional at Center for Financial Planning Inc.® Tim earned a place on Forbes’ Best-In-State Wealth Advisors List in Michigan¹ in 2026 for the ninth consecutive year.

Any opinions are those of the author and not necessarily those of Raymond James. There is no guarantee that these statements, opinions, or forecasts provided herein will prove to be correct. This material is being provided for information purposes only and is not a complete summary of all available data necessary for making an investment decision and is not a recommendation. Investing involves risk, and investors may incur a profit or a loss regardless of strategy selected. No investment strategy can guarantee your objectives will be met. Past performance may not be indicative of future results. Prior to making an investment decision, please consult with your financial advisor about your individual situation.
Q2 2026 Investment Commentary

The Center Contributed by: Center Investment Department

Print Friendly and PDF

As the summer and midterm election season heats up, markets have cooled but ended the quarter on a very positive note after a bumpy start to the year that was caused by the U.S./Iran conflict. From excitement surrounding the SpaceX IPO to a new Chair of the Federal Reserve being sworn in, there has been no shortage of attention-grabbing headlines! The markets ended positive across the board, while volatility has moderated this quarter with periodic shocks based on geopolitical headlines. The Iran war has lasted longer than anticipated, but the economy here in the U.S. remains on track for solid positive growth when you look at real-time statistics like TSA screenings, credit card spending, restaurant bookings, and retail spending in spite of higher gas prices.

Performance Recap

As of June 30, 2026, we have seen quite a turnaround in performance from the first quarter of this year. Bonds posted a positive return of 0.62% during the first half of the year (Bloomberg Barclays Aggregate Bond Index), the S&P 500 ended up 10.21%, and international stocks were the clear winner again so far this year, with the MSCI ACWI Ex-USA at +13.68%. The question remains: what do we see driving returns for the rest of the year?

Elections & Midterms

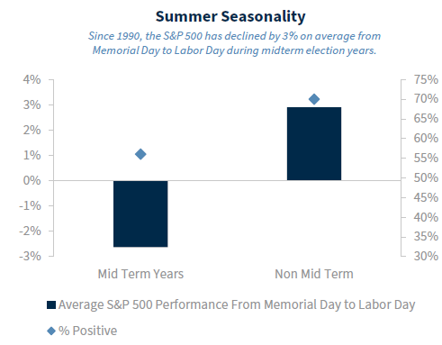
Since Memorial Day, the momentum of positive returns in April and May stalled near market highs. This is not uncommon in a midterm election year. In fact, about half of the time, the S&P 500 has lost money during a midterm election summer, averaging a decline of nearly 3%. This is common because of the political rhetoric leading into election season.

Chart comparing S&P 500 Memorial Day-to-Labor Day performance since 1990, showing average declines during midterm election years and average gains during non-midterm years.

Source: Raymond James, Factset Data as of 5/31/2026 (past performance is not indicative of future results)

Midterm election years have historically been among the more volatile periods in the presidential cycle due to uncertainty around policy, taxes, regulation, and congressional control. Once election outcomes become clearer, markets often refocus on economic fundamentals, and the 12 months following midterm elections have frequently produced stronger returns. History doesn't repeat exactly, but it often rhymes. It is important to stay focused on investing fundamentals during this time:

  • Stay diversified.

  • Rebalance when appropriate.

  • Avoid emotional decisions.

  • Focus on long-term objectives.

  • Keep adequate liquidity for near-term needs.

IPOs & SpaceX

We had one of the most highly anticipated and highly media-covered initial public offerings in history this past quarter as SpaceX raised over $75 billion for its operations and growth ambitions.

At $75B, the total market cap of SpaceX was being valued at ~$1.8T, which would put it in the top 10 holdings of the S&P 500 based on size... BUT it will not be added to the S&P 500 anytime soon. Other indexes made exceptions to their rules-based methodologies so that SPCX would be included in their holdings (and in turn held in ETFs that tracked those indexes), and active managers were welcome to begin trading the stock once it became public, but the S&P 500 stuck to its process, which includes criteria that keep SPCX out of the index for the time being. SPCX isn’t currently profitable (it lost $5B in 2025) and also hasn’t been trading for the one-year minimum that S&P uses in its index yet... we’ll check back next year!

Iran, Oil, and Inflation

The Iran conflict continued to weigh on markets in Q2. It is a continuation of the geopolitical turmoil that has been affecting markets recently (we spoke about this last quarter as well). It has been a dizzying timeline to follow between attacks, potential ceasefires, more attacks, more ceasefires, blockades, memorandums of understanding followed immediately by more attacks to end the quarter... the story changed by the day. This uncertainty, centered heavily on disruptions in the Strait of Hormuz (a critical chokepoint for ~20% of global oil trade), created meaningful volatility.

Oil prices shot up in March, stayed elevated through most of the quarter, and only just recently began to fade as optimism around Hormuz traffic began to pick back up. Volatility, as measured by the VIX Index, spiked back in March but fell quickly as stocks powered through the flurry of headlines.

To us, this has been yet another reminder to focus on the long term and stick to your investing plan. We cannot predict what the market will bring day to day or month to month, but a disciplined investment process kept us invested through the noise and allowed us to rebalance through the volatility to achieve positive investment outcomes.

The Fed & Kevin Warsh

The Fed’s new chair, Kevin Warsh, began his tenure this quarter in a relatively quiet fashion. Just as the market expected leading into the meeting, there were no changes to the federal funds rate or immediate monetary policy. There were some things worth noting from the meeting, such as the fact that Kevin Warsh reiterated that he will not be participating in the “dot plot” projections, and that the rest of the Fed members who did participate mostly shifted their view of inflation and the near-term federal funds rate to remain higher. That feeds into bond market expectations and can have some meaningful impact on our bond allocations. Kevin Warsh also unveiled some new initiatives and task forces that he is implementing at the Fed to restructure its focus and the way it conducts monetary policy going forward.

Values Webinar Recap

In the What Matters Most webinar held in April, Planner & Partner Kali Hassinger, CFP®, CSRIC®, and Portfolio Administrator Mallory Hunt explored the powerful connection between personal values, life goals, and financial decision-making. Rather than focusing solely on investment performance or financial products, the discussion encouraged individuals to begin with what matters most to them—whether that is family, purpose, security, charitable giving, career flexibility, or retirement aspirations—and then build a financial strategy that supports those priorities.

The webinar challenged attendees to think beyond traditional financial goals by identifying the beliefs and values that drive those goals in the first place. Once established, these core values can serve as a financial "North Star," helping individuals stay the course during periods of uncertainty or major life transitions, such as retirement, the loss of a loved one, or a career change. Building a financial plan on a foundation of values provides a consistent framework to return to, allowing decisions to be made with intention rather than emotion during stressful or uncertain times.

At their core, values define the "why," while goals define the "how." From there, financial strategies can be implemented to support both. For example, individuals who prioritize philanthropy may incorporate charitable planning tools such as Donor-Advised Funds (DAFs) or Qualified Charitable Distributions (QCDs) into their overall financial strategy. Values can also influence investment decisions. Environmental, Social, and Governance (ESG) investing, for instance, can be incorporated alongside a core portfolio to help align investment choices with personal beliefs and priorities.

The webinar highlighted how values-based financial planning can create greater clarity, confidence, and intentionality around financial decisions. Practical examples were provided to help individuals identify their core values, align their financial goals with those values, and evaluate financial choices through a more personal and meaningful lens. Ultimately, the overarching message was that a well-designed financial plan is about more than building wealth—it should serve as a tool for aligning financial resources with the life you want to live and the goals that matter most to you.

Thank you for reading this quarter's Investment Commentary. We appreciate the opportunity to share these insights with you. As always, market conditions and personal circumstances can change, but staying focused on your long-term goals remains important. If you have any questions about your investments, financial plan, or any of the topics discussed, our team at The Center is here to help. Please reach out to your advisor to start the conversation. We value your trust and look forward to continuing to serve as a resource for your financial planning needs.

Nicholas Boguth, CFA®, CFP® is a Senior Portfolio Manager and Associate Financial Planner at Center for Financial Planning, Inc.® He performs investment research and assists with the management of client portfolios.

Mallory Hunt is a Portfolio Administrator at Center for Financial Planning, Inc.® She holds her Series 7, 63 and 65 Securities Licenses along with her Life, Accident & Health and Variable Annuities licenses.

Angela Palacios, CFP®, AIF®, is a partner and Director of Investments at Center for Financial Planning, Inc.® She chairs The Center Investment Committee and pens a quarterly Investment Commentary.

Any opinions are those of Angela Palacios, CFP®, AIF®, Nick Boguth, CFA®, CFP®, and Mallory Hunt and not necessarily those of Raymond James. The information contained in this report does not purport to be a complete description of the securities, markets, or developments referred to in this material. There is no assurance any of the trends mentioned will continue or forecasts will occur. The information has been obtained from sources considered to be reliable, but Raymond James does not guarantee that the foregoing material is accurate or complete. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation.

Investing involves risk and you may incur a profit or loss regardless of strategy selected. The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represent approximately 8% of the total market capitalization of the Russell 3000 Index. The MSCI EAFE (Europe, Australasia, and Far East) is a free float-adjusted market capitalization index that is designed to measure developed market equity performance, excluding the United States & Canada. The EAFE consists of the country indices of 22 developed nations. The Bloomberg Barclays US Aggregate Bond Index is a broad-based flagship benchmark that measures the investment grade, US dollar-denominated, fixed-rate taxable bond market. Keep in mind that individuals cannot invest directly in any index, and index performance does not include transaction costs or other fees, which will affect actual investment performance. Individual investors’ results will vary. Investing in oil involves special risks, including the potential adverse effects of state and federal regulation and may not be suitable for all investors. Past performance does not guarantee future results. Diversification and asset allocation do not ensure a profit or protect against a loss. Investing involves risk and you may incur a profit or loss regardless of strategy selected. Past performance is not a guarantee or a predictor of future results. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional.
Employee Stock Options: What Really Matters from Grant to Sale

Green road sign reading “Options Just Ahead” against a bright sky, symbolizing employee stock options, financial opportunities, and long-term wealth planning.

Robert Ingram Contributed by: Robert Ingram, CFP®

Print Friendly and PDF

Non-qualified stock options (NQSOs) are a form of employer compensation that gives an employee the right to purchase a specific number of company shares at a predetermined price within a defined time period. Unlike direct stock grants Restricted Stock Units (RSUs), which provide actual shares of stock, NQSOs offer the option, but not the obligation, to buy shares in the future.

If you have access to these stock options, they can be one of the most valuable opportunities to build wealth through your employer—but they are also frequently misunderstood. On the surface, it might seem straightforward: you can buy your company’s stock at a set price and benefit from future growth. In practice, stock options involve a series of decisions that can have financial and tax consequences that unfold over time. From grant and vesting to exercise and eventual sale, each stage in the lifecycle of these NQSOs carries its own rules and implications for the value you ultimately realize.

Grant: It Starts with a Promise (Not Ownership)

When your company grants you stock options, you don’t actually receive stock. You receive something much more subtle: the right to buy stock later at a fixed price.

You’re told:

  • How many options you have (number of shares you could buy)

  • At what price you’ll be able to buy them (exercise price)

  • When you’ll be allowed to use that right (the vesting schedule)

  • And when the opportunity expires

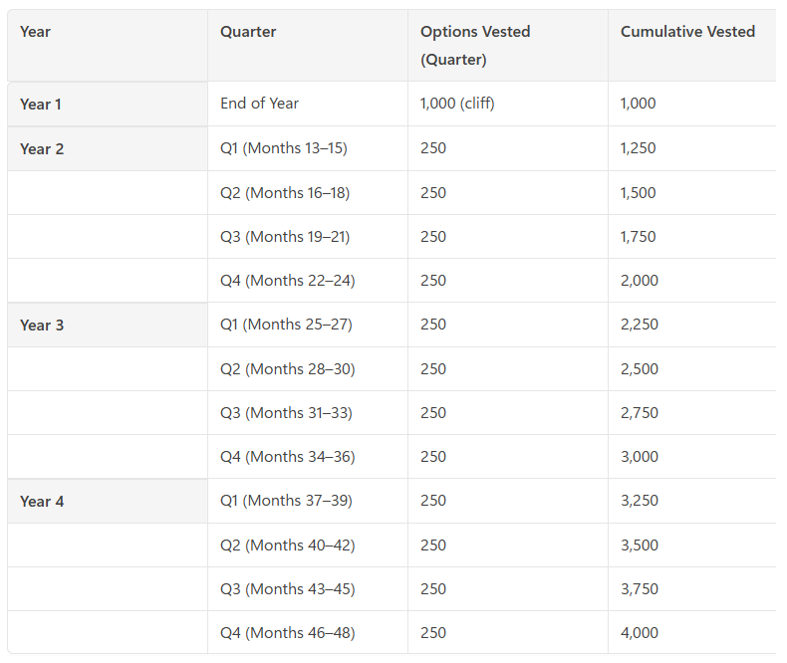
As a hypothetical example, let’s say you were granted 4,000 options on May 1st, 2026, with an exercise price of $20 per share. The vesting schedule is that 25% of the total options vest after one year, and the remaining 75% of the options vest quarterly over the next three years. Finally, the expiration date is May 1st, 2036 (10 years from the grant date). Whoa! There’s a lot there. Let’s tackle it in stages.

At this stage, nothing has happened financially. No cash or value is exchanged. There are no actionable steps, and there is no taxation. There is just the potential opportunity that begins when your options vest.

Vesting: You Earn the Right to Act

Over time, those options that were granted “vest.” This means that the options become exercisable. The option becomes “yours,” and you can choose to exercise (or not exercise) the options (i.e., purchase shares with some or all of the vested options).

In most employee stock option plans, vesting is gradual, often spread out over a few years.

In our example above, the first 1,000 options vest one year from the grant date, so they would be exercisable on May 1st, 2027. From there, portions of the unvested shares vest each quarter for the next three years.

The following table illustrates how a vesting schedule might look, where each quarter an equal number of options vest from the end of year 1 until the end of year 4.

tock option vesting schedule table showing 4-year NQSO vesting with 1-year cliff and quarterly vesting thereafter, totaling 4,000 options

While this is a common type of vesting schedule, it is very important to understand your own employer’s specific vesting plan and to know when your options will be available to exercise. Until the options vest, they are not truly “yours,” and you may forfeit any future right to exercise them if you leave the employer, for example.

But here’s a key point about each vesting date: at vesting, still nothing happens financially. Vesting does not trigger taxes.

This is different from other types of equity compensation, such as Restricted Stock Units (RSUs). When RSUs vest and you receive shares, the total value of the shares at that time is considered income and would be reported and taxed as ordinary income.

When non-qualified stock options vest, there is still no action taken, and you haven’t received the value of any options, so there is no reported income or associated taxes. But now, your planning and decision-making start.

Exercising: When You Buy—and Taxes Kick In

Eventually, you reach the first decision point: do you exercise your options?

The value of stock options comes from the difference between what you’re allowed to pay for the stock and what it’s actually worth in the market.

So, from our example, let’s say you have options that have vested, and the value of the stock in the market is $45 per share. Because your options have an exercise price of $20 and you could purchase shares for $20, there is a gain of $25 per share ($45 - $20). The options allow you the opportunity to build that value without having to buy the shares outright (yet!).

Now, when you do exercise options (i.e., buy the shares) at any time up until the expiration date, this is where things change and taxes come into play.

At the time you exercise, the difference between the market value of the shares and the price you are able to pay to buy them is considered income and is reported to the IRS. In our example, if the value at the time of exercise is $45 per share and your purchase price is $20, you would have ordinary income of $25 per share.

If you exercised 1,000 shares, that would be 1,000 × $25 → $25,000 in taxable income.

Many people assume taxes happen when they sell the shares. While sales can and often do occur around the same time as the exercise, the exercise itself often triggers the biggest tax impact.

If you choose to exercise options in a high-income year, the extra income may push you into higher tax brackets. Another scenario is waiting to exercise large groups of options all at once. This could also dramatically change your overall income in that year and therefore impact your tax liability. This is why careful tax planning is an important part of managing your stock options.

Quick Note on Taxes at Exercise (and How They’re Paid)

Taxes here aren’t just reported and owed—they’re typically withheld. Employers are generally required to withhold taxes at the time of exercise. This usually includes federal taxes, state income tax, Social Security, and Medicare (FICA taxes). How is the withholding paid?

Methods for covering taxes:

  • Cash payment (out of pocket) – sending payment from your bank or wire transfer to cover the taxes

  • Selling shares to cover – the plan sells a portion of exercised shares to cover the taxes

    • This is the most common approach used

  • Withholding shares – the plan withholds a number of shares equal in value to the taxes instead of selling shares on the market

    • This is less common for public company stock option plans

Selling Shares: Turning the Value into Cash

To fully realize the usable value of the options and shares, you would sell the shares for cash as the final financial outcome and decision.

Taxes may come into play again after you exercise and sell your shares (as capital gains or losses).

Remember, at exercise, the difference between the market value and the exercise price is already taxed as income, so the cost basis of the exercised shares becomes the market value at the time of exercise.

Cost basis in our example: if exercising shares when market value was $45 → cost basis = $45

If you were to sell those shares for $55, for example → you would have a $10 capital gain.

If, on the other hand, you sold the shares at $35 → you would have a $10 capital loss.

Depending on when you choose to sell your exercised shares, you could have a short-term capital gain or loss (if held for less than one year) or a long-term capital gain or loss (if held for more than one year). With the tax treatment differences between short-term and long-term capital gains, this again adds further tax planning considerations to your decisions.

Note: You are typically responsible for any taxes associated with these capital gains or losses, as they are not withheld by the employer plan.

From Exercise to Ownership to Selling: (How You Get There)

When you exercise your options, you’re no longer holding an option—you now own stock. There is generally no maximum holding period before having to sell, and there is no risk of losing rights to the shares if you leave the employer, retire, etc.

But there are a few methods for exercising options and turning them into real value.

  • Pay in cash (hold all shares) – covering the cost of the share purchases and usually the tax withholding by writing a check or transferring funds to the plan administrator. You retain all of the shares until you decide to sell some or all of them.

At this point, you might be asking, “What if I don’t have the cash, or I don’t want to use my funds to exercise the options?”

Cashless Exercise:

  • Sell some shares at exercise (hold some shares) – a portion of shares is sold immediately to cover the cost of the shares exercised (and usually the tax withholding). You retain the remaining shares.

You would then hold the remaining shares for investment until you decide to sell them.

The other type of cashless exercise is one of the most common methods for using options and converting them into usable value:

  • Cashless exercise (sell everything) – you exercise options, and all the shares are sold immediately, covering the cost of shares and taxes, leaving you with cash proceeds instead of stock.

This full cashless exercise allows you to turn the value of your options into cash in one step with no out-of-pocket cost and avoids the ongoing risk of holding the stock. That can be very advantageous for many people.

However, there may be cases where exercising options to hold shares makes sense. One advantage is that potential future growth may be taxed at capital gains rates, which could be lower than ordinary income rates. Depending on your current income and expected future income, this difference may significantly impact your overall outcome.

Bottom Line

Stock options are more than just a one-time benefit. They involve a process and decisions based on many factors over several years (even a decade or longer). Small differences in timing, taxes, and personal choices at each step add up to shape your results.

As with many complex financial decisions that have tax and other implications, you should consult with your financial planner and tax advisor.

If you’ve received stock options and aren’t completely confident in how they fit into your overall plan, we’re happy to have a conversation.

Please don’t hesitate to contact us!

Robert Ingram, CFP®, is a CERTIFIED FINANCIAL PLANNER™ professional at Center for Financial Planning, Inc.® With more than 15 years of industry experience, he is a trusted source for local media outlets and frequent contributor to The Center’s “Money Centered” blog.

Securities offered through Raymond James Financial Services, Inc., member FINRA/SIPC. Investment advisory services are offered through Center for Financial Planning, Inc. Center for Financial Planning, Inc. is not a registered broker/dealer and is independent of Raymond James Financial Services.

The foregoing information has been obtained from sources considered to be reliable, but we do not guarantee that it is accurate or complete. Any opinions are those of Bob Ingram, CFP® and are not necessarily those of RJFS or Raymond James. Raymond James Financial Services, Inc. and its advisors do not provide advice on tax issues, these matters should be discussed with the appropriate professional.

Finding the Perfect Mix: How to Build the Right Asset Allocation for You

The Center Contributed by: Center Investment Department

Print Friendly and PDF

Most delicious meals start with a great recipe. A recipe tells you which ingredients to use — and how much of each — to create something satisfying. In the same way, successful investing begins with understanding the right mix of assets that can help you reach your goals and stay comfortable along the way. Just as tastes and ingredients change or are tweaked over time, markets are ever evolving, so what has worked in the past may need periodic adjustments and thoughtful updates.

Determining the Right Mix

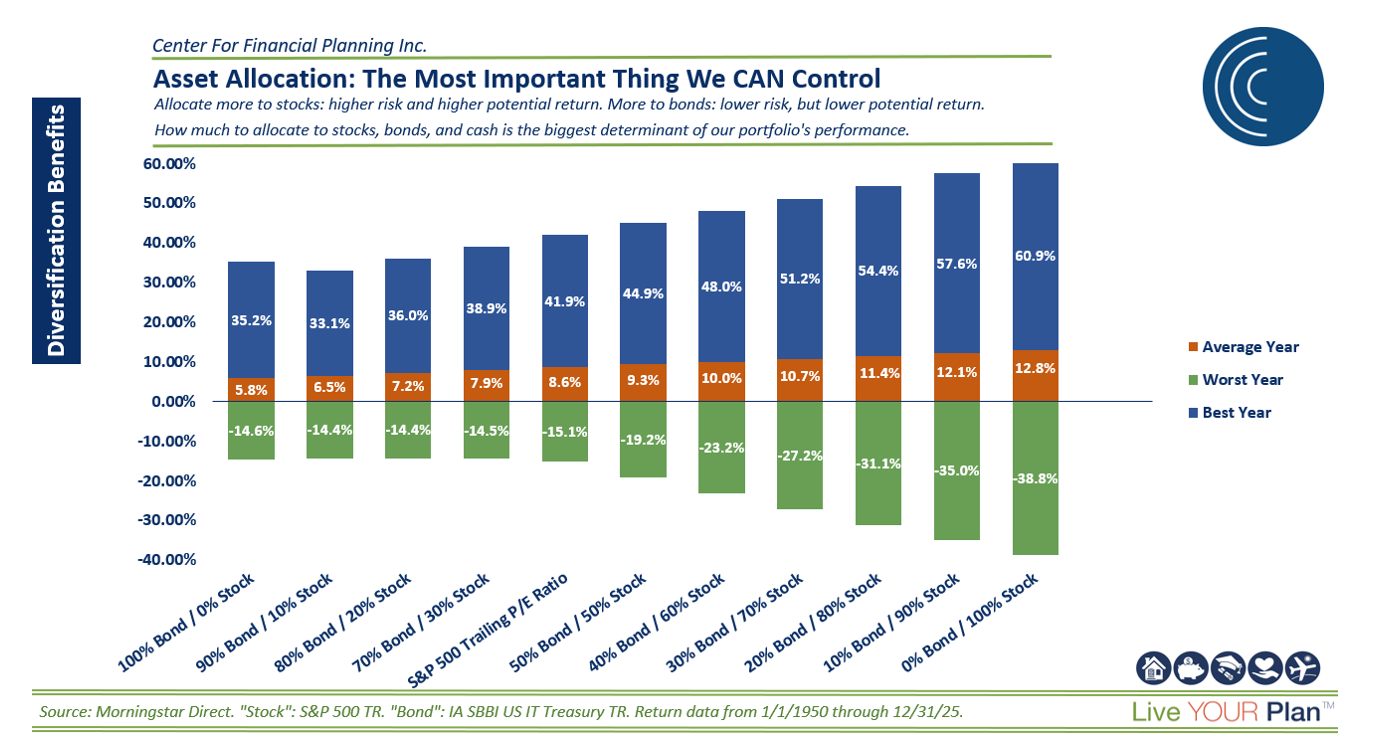
Asset allocation remains one of the most important drivers of long‑term investment outcomes and one of the few things investors can influence. It’s the foundational blend of stocks, bonds, and cash that shapes how your portfolio behaves, so choosing the right mix matters. This concept is perfectly depicted in the chart below, created by my colleague, Nick Boguth, CFA®, CFP®. This chart illustrates different asset allocation mixes and how they have historically produced varying ranges of outcomes. Portfolios with higher stock allocations have experienced higher best‑year returns but also greater drawdowns in worst‑year periods, while more conservative allocations (those with higher bond allocations) have shown narrower return ranges. This really highlights the trade‑off between risk and return that investors should consider when constructing a portfolio.

Visual chart illustrating how different asset allocation mixes of stocks and bonds impact best‑year, average‑year, and worst‑year investment returns, highlighting the tradeoff between risk and potential reward

Now, choosing that mix may look different today than it did several years ago—it’s not static. And it might look different again in the future. To determine what will work best for you, start by answering three core questions:

  1. What are my financial goals?

  2. When do I need to achieve them?

  3. How much will I be investing now — and over time — to support those goals?

Seasoning to Taste: Understanding Your Risk Tolerance

Even the perfect recipe can fall flat if it doesn’t match your palate. The same is true with investing. Imagine the equity market falls 20%. Would you feel tempted to sell stocks and flee to bonds or cash? Whether we like it or not, volatility has become a constant feature of today’s market environment, driven by changes in inflation, Federal Reserve policy shifts, and global uncertainty. We need to take these factors along with others, into consideration, and this is where risk tolerance comes into play. Understanding your comfort level with volatility and loss helps you select an allocation you can stick with, especially during challenging periods. When evaluating your tolerance, consider the risks and rewards associated with different investment types, how you react to market stress, how much loss you could tolerate for long term gains, and whether your emotions align with your strategy. Your feelings and behaviors matter just as much as the math.

Following the Recipe: Staying Disciplined

Just like sticking closely to a recipe produces more consistent results, staying committed to your asset allocation greatly increases your chances of long‑term success. But don’t get me wrong—it isn’t always easy!

Temptations to chase performance, react to alarming headlines, or invest in the “next big thing” are always present. Emotional responses to market swings, fear of missing out, and short‑term noise can all pull investors away from a thoughtfully designed plan, and often at exactly the wrong time. Over time, these small deviations can meaningfully change the risk and return profile of a portfolio. Several basic practices can help reinforce discipline and keep your plan on track:

  • Diversification: Spreading investments across asset classes and regions can help manage risk‑adjusted returns and potentially reduce reliance on any single outcome.

  • Regular Rebalancing: Periodically resetting your portfolio helps manage risk, maintain alignment with your goals, trim positions that have grown too large, and add to areas with future potential.

  • Dollar‑Cost Averaging: Investing consistently over time can help reduce the impact of market volatility and remove the pressure of timing decisions.

Bringing It All Together

We believe finding the right asset allocation is one of the most important steps in building a sound investment plan. By clarifying your goals, timeline, resources, and risk tolerance, you can create a mix that works for you.

Markets will continue to change, but the fundamentals don’t. Define your recipe, understand your palate, and follow the process with discipline. A consistent approach may help support long term investment objectives.

Securities offered through Raymond James Financial Services, Inc., member FINRA/SIPC. Investment advisory services are offered through Raymond James Financial Services Advisors, Inc.

Center for Financial Planning, Inc. is not a registered broker/dealer and is independent of Raymond James Financial Services.

This information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Any opinions are those of the author and are not necessarily those of RJFS or Raymond James. Every investor’s situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment or investment decision. Investing involves risk, investors may incur a profit or loss regardless of strategy or strategies employed. Asset allocation does not ensure a profit or guarantee against a loss.

Dollar-cost averaging cannot guarantee a profit or protect against a loss, and you should consider your financial ability to continue purchases through periods of low price levels.

Q1 2026 Investment Commentary

Print Friendly and PDF

Executive Summary

  • Markets faced early volatility driven by geopolitical tensions, higher oil prices, tariff uncertainty, and evolving Fed policy.

  • Stocks declined modestly (S&P 500 down ~4%), while bonds were essentially flat, cushioned by higher yields.

  • Oil and gold were volatile, reminding investors that even “safe haven” assets can move unexpectedly.

  • The Federal Reserve held rates steady, despite market swings in rate-cut and rate-hike expectations.

  • Diversification mattered—spreading risk across asset classes and sectors helped limit portfolio drawdowns.

  • Long-term investors are best served by staying disciplined, maintaining liquidity needs, and avoiding emotional decisions during short-term market noise.

Volatility is a normal part of investing. A thoughtful financial plan and a diversified portfolio remain the most reliable tools for navigating uncertain markets.


2026 is off to an eventful start, reminding us once again that volatility is a normal part of the investing journey. A wide variety of headlines, mostly geopolitical, have dominated the year so far, creating early volatility across equities, commodities, and even bonds. First, the U.S. military arrested the Venezuelan  President Nicolás Maduro and his wife, forcing a change in leadership for the country. Gold and silver surged, while defensive sectors like U.S. energy and utility stocks rallied. Shortly after, the U.S. made statements about the possibility of controlling Greenland, which strained relations with Denmark and NATO partners. Lastly, the U.S. re-entered conflict in the Middle East as war broke out in the region with Iran.  With traffic through the Strait of Hormuz restricted, global oil markets felt the impact as the price for a barrel of oil quickly spiked to well over $100 and hovered there for the remainder of the quarter.

Bonds, as measured by the Bloomberg US Aggregate Bond index, ended the quarter essentially flat at -0.05% while U.S. stocks (S&P 500) were down -4.33%. International markets and U.S. small-cap markets started the year with surprising strength, but they have given back much of those gains through March as the war escalated. Gold experienced the most volatility, rallying another 20% this year before giving nearly all of that back, and ended the quarter up only 5.7%. In our recent investment event, we discussed many of these headlines and noted that this is a midterm election year, which is usually marked by greater-than-average volatility but often ends positively.

Volatility Caused by Geopolitical Events

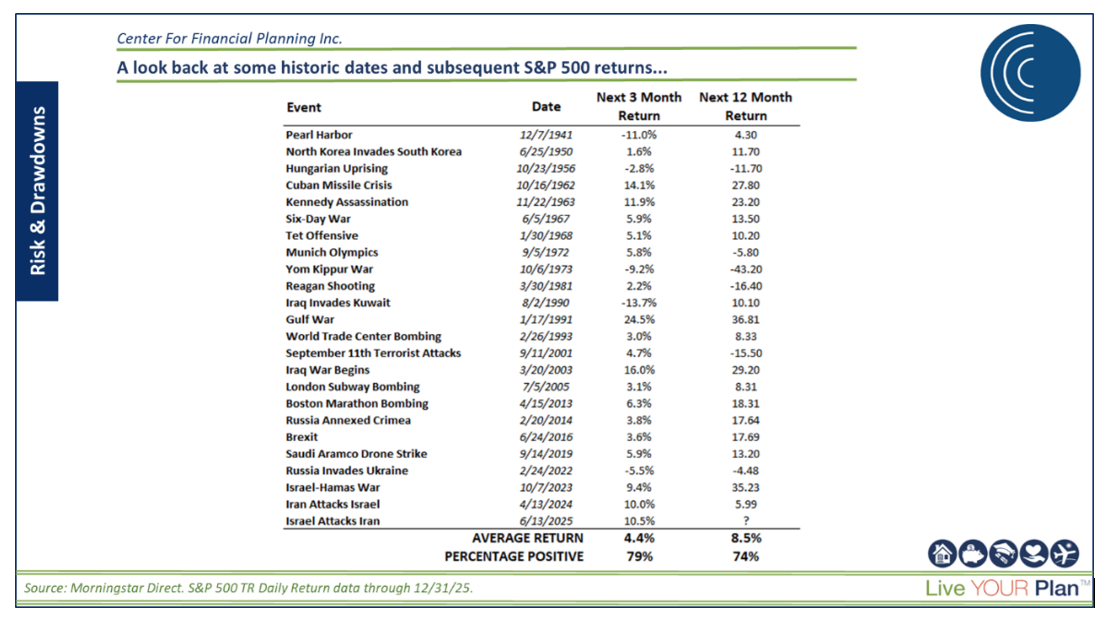
The above headlines can make investors want to act – maybe even sell their investments and stock up on cash under the mattress or gold bars in the safe. In times of stress, it is important to lean on history and data to guide the next best course of action. See below for stock returns 3 and 12 months after key conflicts over the past 100 years. Does the data surprise you?

Table showing S&P 500 returns after major historical events, including wars, terrorist attacks, and political crises, comparing 3‑month and 12‑month market performance.

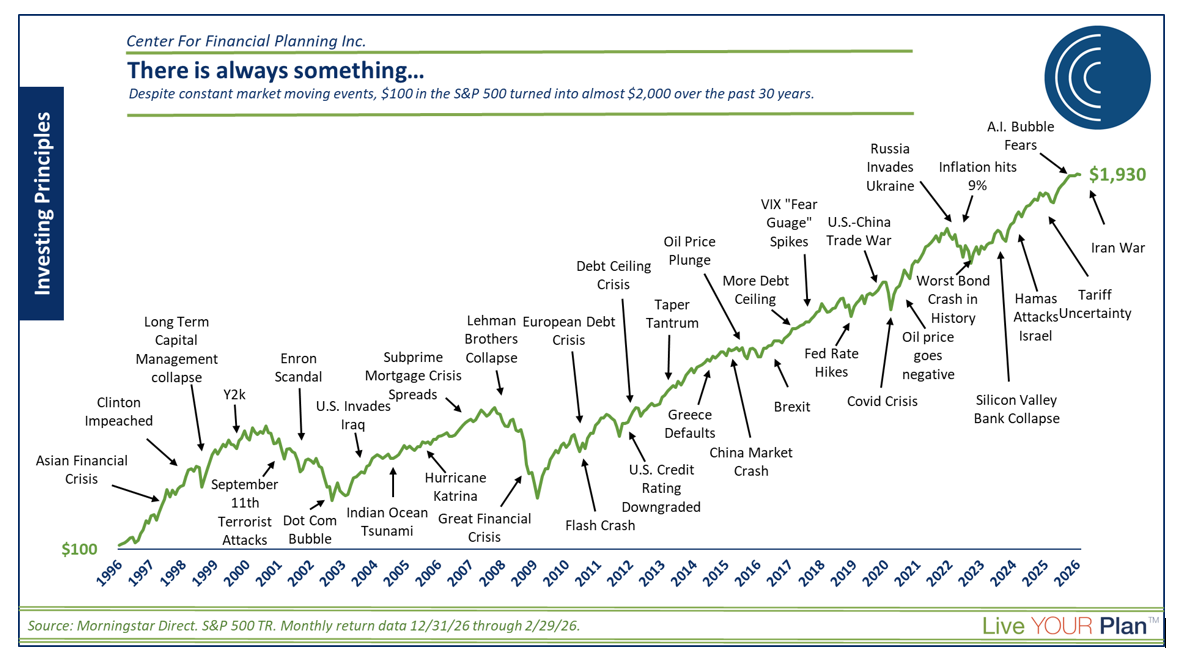
Diversification and remaining invested are very important in times like these. While diversification doesn’t completely insulate you from drawdowns during the hard times, it does make them much more bearable and hopefully sets your portfolio up for a quicker recovery. Volatility is a normal part of investing. Remember, if we had no risk, there would also be no reward. It is the price we pay for long-term positive returns. Each year, volatility crops up for one reason or another, and temporary pullbacks are very normal.

Line chart showing long‑term growth of $100 invested in the S&P 500 rising to nearly $2,000 over 30 years, despite major market shocks such as wars, recessions, inflation, and financial crises.

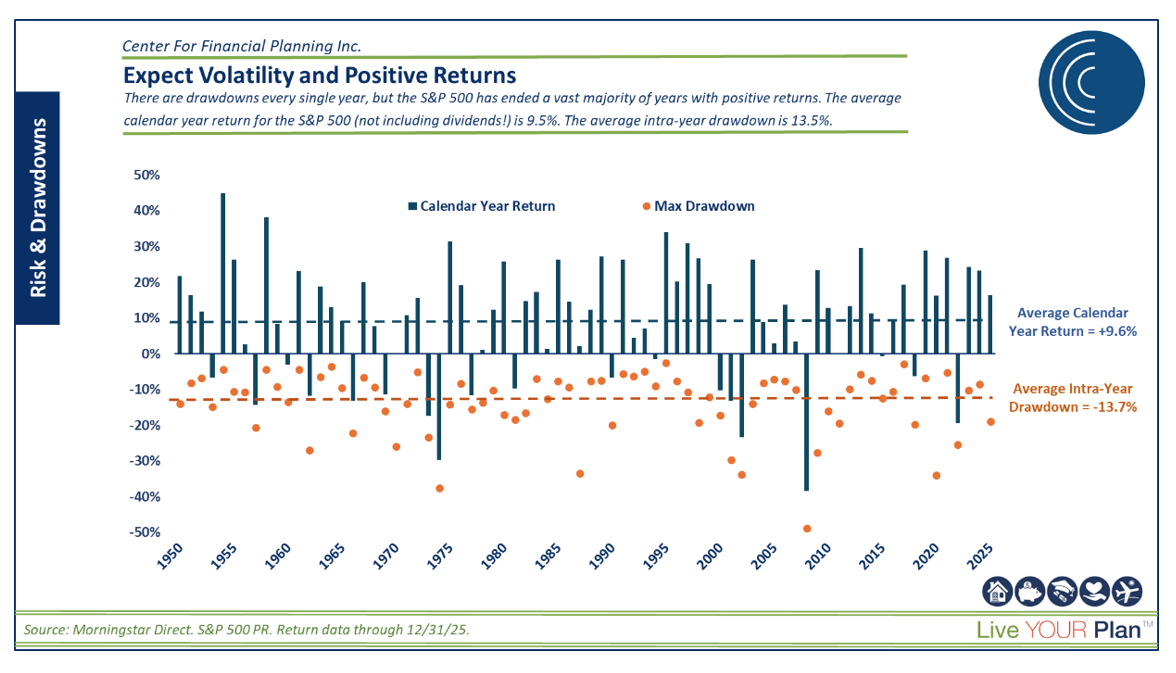
2025 and 2026 have been no exception. Liberation Day (political branding of tariff policies) caused a strong market pullback around the same time last year, followed by the Iran War this year. The chart below shows the regularity of pullbacks. The blue bars (overwhelmingly positive) are calendar year returns. The orange dots show how much the market fell WITHIN each calendar year. Some years only see 3% to 10% dips. Some years see dips of 10% to 50%. The “average” intra-year drawdown since 1950 is 13.5%. Despite those dips, the S&P 500 was positive ¾ of the time and averaged 9.5% per year.

Chart showing annual S&P 500 calendar returns and maximum intra‑year drawdowns over time, illustrating that market volatility occurs every year while long‑term returns are usually positive.

For investors with long time horizons, these moments may serve as great entry points, especially if you have additional dollars to save. For those who depend on their assets, we have an action plan in place that was developed long before this volatility began. The thoughtful planning work we do with you helps ensure you have what you need for the next 6 months, a year, or even two years, already in cash or money market, which means you don’t have to sell into market volatility.

Federal Reserve and Interest Rates

The Federal Reserve (The Fed) has faced political pressure to cut interest rates while it navigates stubborn inflation, a weakening labor market, and the economic consequences of the war in Iran. The Fed opted to hold interest rates steady at 3.5%–3.75% through its January and March meetings, even as oil‑price spikes linked to Middle East conflict complicated its inflation outlook. It is important to remember that the Fed focuses on core PCE, which strips out inflation pressures from energy and food because they are typically so volatile. Inflation fears and concerns that the Fed could raise short-term interest rates have picked up again amid the spike in oil prices. I think we all immediately remember the 1970s era of inflation when we hear that oil is getting expensive and start to worry. As of now, this spike has been short-lived, and if the Straits of Hormuz reopen soon and oil starts moving again, we should see oil prices start to come back down. Short-term spikes usually don’t flow through to core PCE inflation in a meaningful way. However, if oil remains scarce and prices remain high, you will start to see the higher energy costs leak through to other areas of the economy, which would then be reflected in higher core PCE.

The bond market immediately jumped to the conclusion in March that the latter would happen, and the Fed would be staring at rising inflation numbers, and then further assume the Fed would start raising interest rates again to combat this inflation. We think it is far too early to assume this will happen. We entered the year with bond and equity markets pricing in 1 or 2 rate cuts by the end of this year, and now the market is pricing in a rate increase before year's end. This change in expectations is why bonds have had a negative month of returns. However, it is important to note that this isn’t the start of a 2022 bond market again. Now we are starting from a place of much higher yields, and we still have a robust interest rate being paid to us every month to compensate for some volatility.

Despite market assumptions, Fed officials continue to project one rate cut later in 2026, but internal disagreement continues, and if Kevin Warsh is confirmed by the Senate to take over in May, opinions could shift. It is important to remember that no single person sets this policy. There are 12 voting members of the Federal Open Market Committee (FOMC) who determine the fate of interest rates. The Chairman is simply the public representative of this board, and the chairperson only has 1 vote like everyone else and has no veto power.

At the same time, political pressure from President Trump on the Fed continues, as he publicly called for an immediate rate cut amid market volatility driven by war. Chair Jerome Powell, nearing the end of his term, emphasized that the Fed is still assessing the impact of the Iran war, elevated oil prices, and mixed economic data, and warned that the path ahead remains deeply uncertain. With leadership transitions approaching and geopolitical risks rising, the Fed’s next move remains far from clear—fueling market anxiety and adding to the perception that 2026 has become one of the most unpredictable years for Fed policy in over a decade.

Long Term Versus Short Term Interest Rates and Mortgage Rates

While the Fed does set interest rate policy, it is important to remember that it only sets short-term rates. Intermediate and long-term interest rates are driven more by supply and demand. Many have hoped that lower short-term rates would equate to lower mortgage rates. While rates have come down over the past 9 months, they have recently (in March) drifted back upward, causing new home buyers to pause. Earlier this quarter, 30-year mortgages had fallen below 6%, but they have drifted back to the mid-6 % range, nearly halting mortgage applications.

Private Credit Fears

Over the past few years, we have gotten many questions on private credit. We are constantly kicking the tires on different investment opportunities and trying to understand if they deserve a spot in your portfolio. The allure of 10%+ interest rates and little volatility sounded very tempting, but it was the first red flag in our review. Limited liquidity also had alarm bells swirling in our heads. Usually, if something sounds too good to be true, it often is. Private credit is no exception. Many dove in, thinking there would be little volatility and a great income stream. The problem with a limited liquidity product is just that, you usually can’t access your money when you most want it. As there were notable headlines about private credit borrowers, these private credit funds faced many redemption requests that they could not fulfill. Imagine wanting to sell an investment and being told no. That fear then starts to snowball, and more investors request redemptions, snowballing the issue and the headlines. We recognized this product for what it is: for high-net-worth investors with very long time horizons who can wait out redemption limitations without needing the cash. Even then, they aren’t guaranteed to pay you a premium investment return. The headlines are likely to continue escalating around these products as barriers to selling persist and securities in the portfolios are marked down to their actual values.

Artificial Intelligence

A.I. news continues to drive headlines and move markets. Companies that are driving the technology forward continue to share new developments and innovations that can be both exciting AND nerve-wracking. There is no shortage of opinion pieces predicting what the future holds for the technology, ranging from “minor” to “world-changing”. This uncertainty has shown up in financial markets, as there is some dispersion in stock prices lately. Not everything is moving in unison…which is healthy! We would not want to see dot-com bubble-era behavior, where any stock that mentioned A.I. was immediately rewarded. Certain companies’ stock prices have fallen following announcements of large A.I. spending plans, while others have reacted positively. Demand for “chips” is driving strong earnings expectations in the semiconductor industry, but there is concern about circular spending, where companies are just paying each other back and forth, and that may not be sustainable. There has also been some major volatility among individual stock names as competitive moats come under attack from A.I. Utilities and commodities are affected as “datacenter” plans with mind-blowing power needs continue to develop.

This is a major theme that affects many parts of the market. With any innovation, uncertainty follows, and all investors can do is invest accordingly. As far as our portfolios go, we continue to monitor valuations and expectations for the stocks and bonds that are directly affected. This quarter's volatility has actually made valuations more attractive. We get the question, “Is this a bubble?” a lot…and we just don’t see it across the whole market. Sure, there might be individual companies trading at extreme valuations, but it certainly isn’t across the entire market. It might surprise you to hear that, for example, Microsoft ended the quarter in a 31% drawdown from its prior high! It is one of the largest holdings in the S&P 500, but due to performance in other sectors, the index was still only down ~4% in Q1. To us, that is yet another example of diversification (in this case, sector diversification within the S&P 500) leading to better outcomes for investors.

Tariff Update

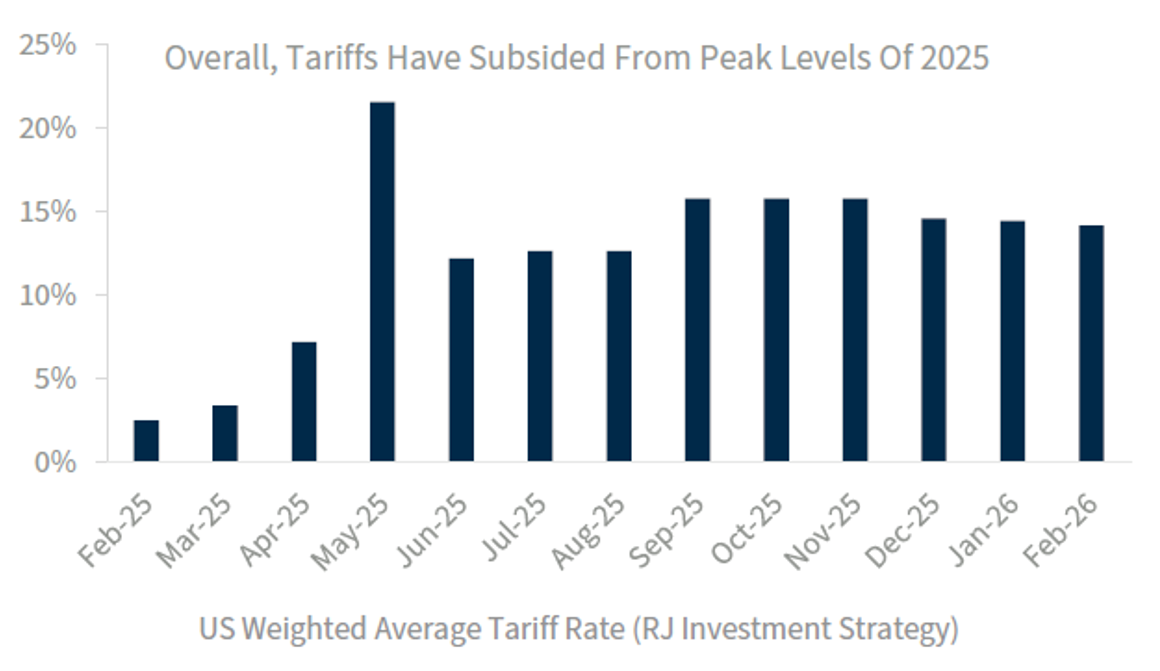
Trump’s tariffs were another source of volatility in the first quarter. The Supreme Court ruled that a portion of Trump's tariffs, the ones imposed on specific countries, were unlawful. Trump’s initial justification for imposing those tariffs as a national “emergency” did not hold up in the Supreme Court, so those tariffs were removed. He immediately responded to this ruling by imposing new temporary tariffs of 10%, then later 15%. Ultimately, this is a fluid situation that is adding to the uncertainty in the stock and bond markets. Companies have to navigate pricing and supply chain issues arising from tariff uncertainty, and there is still the lingering question of whether tariff refunds will be paid out.

Bar chart showing the U.S. weighted average tariff rate declining from a peak in mid‑2025 and stabilizing through early 2026, according to RJ Investment Strategy.

Overall, it seems we can expect tariffs to remain in place for now, which will ultimately provide another revenue stream for the U.S. government but lead to higher prices for U.S. consumers. Time will tell how these tariffs will change going forward, whether they will remain in place long-term or be used more as a bargaining chip to make deals with other countries.

Gold Crash?

Another surprising market move in Q1 came from Gold. Gold started the year continuing its growth, hitting a new all-time high of almost $5,600 near the end of January! Then it fell 20% from its high over the next month and a half, bottoming out near $4,200 on March 23rd. It rallied slightly and ended the quarter near $4,600/oz.

The market can surprise us more often than we think. Gold is often considered a “safe haven” asset, which you would expect would RALLY in the event of something like, I don’t know, the unknowns of a war in the Middle East. But that is not how gold reacted this past quarter; in fact, headlines at the very end of the quarter hinted at an off-ramp from the conflict with Iran, and gold actually rallied on the news, similarly to stocks! Not exactly the movement you would expect from a “safe haven” asset.

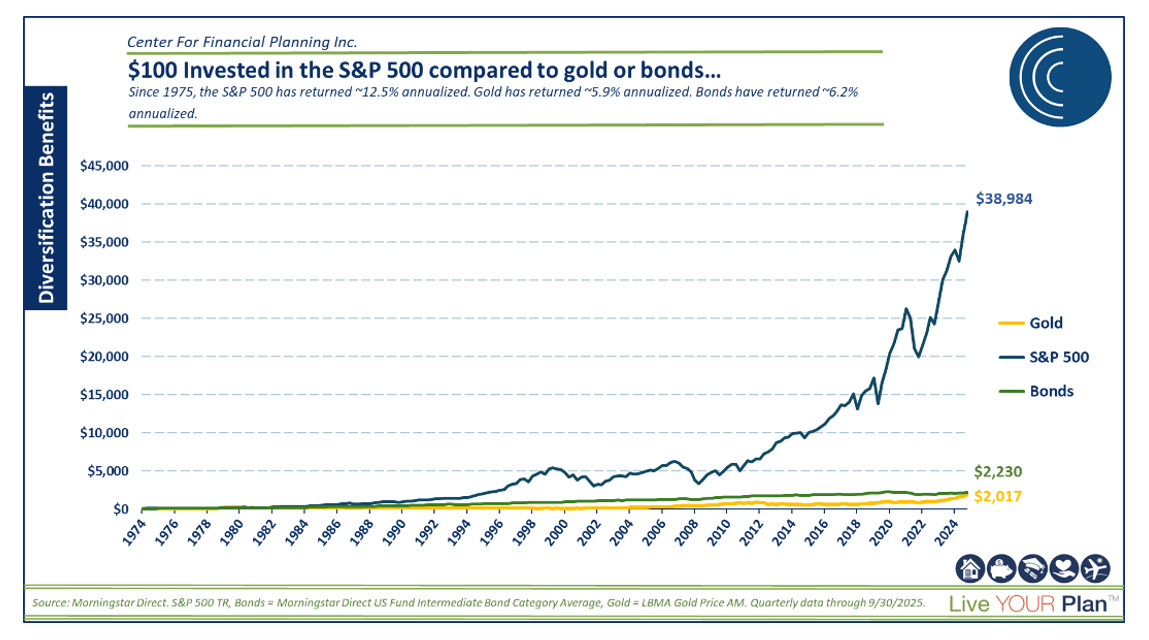
Line chart comparing $100 invested in the S&P 500, gold, and bonds since 1975, showing significantly higher long‑term growth for the S&P 500 than gold or bonds.

Gold is an uncorrelated asset for better or worse. It has been on an amazing run over the past few years and just began experiencing some volatility this past quarter. Like any asset, consider the risks before investing, and understand your unique situation and financial plan to determine if, where, and how gold might fit into your portfolio.

Thank you for taking the time to read this quarter’s investment commentary. There is a lot of noise in the markets, and we believe that a thoughtful financial plan, paired with a disciplined investment process, is more important than ever. Please don’t hesitate to reach out to your financial advisor or anyone on our team here at The Center with any questions. We’re here to help and would be delighted to have a conversation.

Angela Palacios, CFP®, AIF®, is a partner and Director of Investments at Center for Financial Planning, Inc.® She chairs The Center Investment Committee and pens a quarterly Investment Commentary.

Nicholas Boguth, CFA®, CFP® is a Senior Portfolio Manager and Associate Financial Planner at Center for Financial Planning, Inc.® He performs investment research and assists with the management of client portfolios.

Any opinions are those of Angela Palacios, CFP®, AIF® and Nick Boguth, CFA®, CFP® and not necessarily those of Raymond James. The information contained in this report does not purport to be a complete description of the securities, markets, or developments referred to in this material. There is no assurance any of the trends mentioned will continue or forecasts will occur. The information has been obtained from sources considered to be reliable, but Raymond James does not guarantee that the foregoing material is accurate or complete. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy selected.

The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represent approximately 8% of the total market capitalization of the Russell 3000 Index. The MSCI EAFE (Europe, Australasia, and Far East) is a free float-adjusted market capitalization index that is designed to measure developed market equity performance, excluding the United States & Canada. The EAFE consists of the country indices of 22 developed nations. The Bloomberg Barclays US Aggregate Bond Index is a broad-based flagship benchmark that measures the investment grade, US dollar-denominated, fixed-rate taxable bond market. Keep in mind that individuals cannot invest directly in any index, and index performance does not include transaction costs or other fees, which will affect actual investment performance. Individual investors’ results will vary. Investing in oil involves special risks, including the potential adverse effects of state and federal regulation and may not be suitable for all investors. Past performance does not guarantee future results. Diversification and asset allocation do not ensure a profit or protect against a loss. Investing involves risk and you may incur a profit or loss regardless of strategy selected. Past performance is not a guarantee or a predictor of future results. Raymond James and its advisors do not offer tax or legal advice. You should discuss any tax or legal matters with the appropriate professional.

Gold is subject to the special risks associated with investing in precious metals, including but not limited to: price may be subject to wide fluctuation; the market is relatively limited; the sources are concentrated in countries that have the potential for instability; and the market is unregulated.

Retirement Planning Challenges for Women: How to Face Them and Take Action

Sandy Adams Contributed by: Sandra Adams, CFP®

Print Friendly and PDF

If we are being completely honest, planning and saving for retirement seems to be more and more challenging these days – for everyone. No longer are the days of guaranteed pensions, so it’s on us to save for our own retirement. Even though we try our best to save…life happens and we accumulate more expenses along the way. Our kids grow up (and maybe not out!). Our older adult parents may need our help (both time and money). Depending on our age, grandchildren might creep into the picture.  Add it all up and the question is: how are we are supposed to retire? We need enough to potentially last 30 to 35 years (depending on our life expectancy). Ugh! 

While these issues certainly impact both men and women, the impact on women can be tenfold. Let’s take a look at some of the major issues women face when it comes to retirement planning. 

1. Women Have Fewer Years of Earned Income Than Men 

Women tend to be the caregivers for children and other family members. This ultimately means that women have longer employment gaps as they take time off work to care for their family. The result: less earned income, retirement savings, and Social Security earnings. It can also halt career trajectory.   

Action Steps 

  • Attempt to save at a higher rate during the years you ARE working. It allows you to keep pace with your male counterparts.

  • If you are married you may want to save in a ROTH IRA or IRA (with spousal contributions) each year, even if you are not in the workforce. 

  • If you are serving as the caregiver for a family member, consider having a Paid Caregiver Contract drawn up to receive legitimate and reportable payment for your services. This could potentially help you and help your family member work towards receiving government benefits in the future, if and when needed. 

2. Women Earn Less Than Men 

For every $1 a man makes, a woman in a similar position earns 84¢ according to the Bureau of Labor Statistics. As a result, women see less in retirement savings and Social Security benefits based on earning less.  

Action Steps 

  • Again, save more during the years you are working. Attempt to maximize contributions to employer plans. Also, make annual contributions to ROTH IRA/IRAs and after-tax investment accounts. 

  • Invest in an appropriate allocation for your long term investment portfolio, keeping in mind your potential life expectancy. 

  • Be an advocate for yourself and your women cohorts when it comes to requesting equal pay for equal work. 

3. Women Are Less Aggressive Investors Than Men 

In general, women tend to be more conservative investors than men. Analyses of 401(k) and IRA accounts of men and women of every age range show distinctly more conservative allocations for women. Especially for women, who may have longer life expectancies, it’s imperative to incorporate appropriate asset allocations with the ability for assets to outpace inflation and grow over the long term. 

Action Steps 

  • Work with an advisor to determine the most appropriate long term asset allocation for your overall portfolio, keeping in mind your potential longevity, potential retirement income needs, and risk tolerance. 

  • Become knowledgeable and educated on investment and financial planning topics so that you can be in control of your future financial decisions, with the help of a good financial advisor. 

4. Women Tend to Live Longer Than Men 

Women have fewer years to save and more years to save for. The average life expectancy is 82.1 for women and 77.8 for men according to the Centers for Disease Control and Prevention. Since women live longer, they must factor in the health care costs that come along with those years.   

Action Steps 

  • Plan to save as much as possible. 

  • Invest appropriately for a long life expectancy. 

  • Work with an advisor to make smart financial decisions related to potential income sources (coordinate spousal benefits, Social Security, pensions, etc.) 

  • Make sure you have a strong and updated estate plan. 

  • Take care of your health to lessen the cost of future healthcare. 

  • Plan early for Long Term Care (look into Long Term Care insurance, if it makes sense for you and if health allows). 

5. Women Who Are Divorced Often Face Specific Challenges and Are Less Likely to Marry After “Gray Divorce” (Divorce After 50) 

From a financial perspective, divorce tends to negatively impact women far more than it does men. The average woman’s standard of living drops 27% after divorce while the man’s increases 10% according to the American Sociological Review. That’s due to various reasons such as earnings inequalities, care of children, uneven division of assets, etc. 

The rate of divorce for the 50+ population has nearly doubled since the 1990s according to the Pew Research Center. The study also indicates that a large percentage of women who experienced a gray divorce do not remarry; these women remain in a lower income lifestyle and less likely to have support from a partner as they age. 

Action Steps 

  • Work with a sound advisor during the divorce process, one who specializes in the financial side of divorce such as a Certified Divorce Financial Analyst (CDFA) (Note: attorneys often do not understand the financial implications of the divorce settlement). 

6. Women Are More Likely to Be Subject to Elder Abuse 

Women live longer and are often unmarried or alone. They may not be as sophisticated with financial issues. They may be lonely and vulnerable. New reports highlight financial exploitation as the fastest-growing form of elder abuse, disproportionately affecting older women, according to the Transamerica Institute.  

Action Items 

  • If you are an older adult, put safeguards in place to protect yourself from Financial Fraud and abuse. For example: check your credit report annually and utilize credit monitoring services like EverSafe.  

  • Have your estate planning documents updated, particularly your Durable Powers of Attorney documents, so that those that you trust are in charge of your affairs if you become unable to handle them yourself. 

  • If you are in a position of assisting an older adult friend or relative, check in on them often. Watch for changes in their situations or behavior and do background checks on anyone providing services. 

While it is unlikely that the retirement challenges facing women will disappear anytime soon, taking action can certainly help to minimize the impact they can have on women’s overall retirement planning goals. I have no doubt that with a little extra planning, and a little help from a quality financial advisor/professional partner, women will be able to successfully meet their retirement goals.   

If you or someone you know are in need of professional guidance, please give us a call. We are always happy to help. 

Sandra Adams, CFP®, is a Partner and CERTIFIED FINANCIAL PLANNER™ professional at Center for Financial Planning, Inc.® and holds a CeFT™ designation. She specializes in Elder Care Financial Planning and serves as a trusted source for national publications, including The Wall Street Journal, Research Magazine, and Journal of Financial Planning.

Investing involves risk and you may incur a profit or loss regardless of strategy selected, including diversification and asset allocation. Raymond James is not affiliated with EverSafe.

The cost and availability of Long Term Care insurance depend on factors such as age, health, and the type and amount of insurance purchased. These policies have exclusions and/or limitations. As with most financial decisions, there are expenses associated with the purchase of Long Term Care insurance. Guarantees are based on the claims paying ability of the insurance company.

7 Ways the Planning Doesn't Stop When You Retire

Sandy Adams Contributed by: Sandra Adams, CFP®

Print Friendly and PDF

Most materials related to retirement planning are focused on “preparing for retirement” to help clients set goals and retire successfully. Does that mean when goals are met, the planning is done? In my work, there is often a feeling that once clients cross the retirement “finish line” it should be smooth sailing from a planning standpoint. Unfortunately, nothing could be further from the truth. For many clients, post-retirement is likely when they’ll need the assistance of a planner the most!

Here are 7 planning post-retirement issues that might require the ongoing assistance of a financial advisor:

1. Retirement Income Planning - An advisor can help you put together a year-by-year plan including income, resources, pensions, deferred compensation, Social Security and investments. The goal is to structure a tax-efficient strategy that is most beneficial to you.

2. Investments - Once you are retired, a couple of things happen to make it even more important to keep an active eye on your investments: (1) You will probably begin withdrawing from investments and will likely need to manage the ongoing liquidity of at least a portion of your investment accounts and (2) You have an ongoing shorter time horizon and less tolerance for risk.

3. Social Security - It is likely that in pre-retirement planning you may have talked in general about what you might do with your Social Security and which strategy you might implement when you reach full retirement age (which is 67). However, once you reach retirement, the rubber hits the road, and you need to navigate all of the available options and determine the best strategy for your situation – not necessarily something you want to do on your own without guidance.

4. Health Insurance and Medicare - It’s a challenge for clients retiring before age 65 who have employers that don’t offer retiree healthcare. There’s often a significant expense surrounding retirement healthcare pre-Medicare.

For those under their employer healthcare, switching to Medicare is no small task – there are complications involved in “getting it right” by ensuring that clients are fully covered from an insurance standpoint once they get to retirement.

5. Life Insurance and Long-Term Care Insurance - Life and long-term care insurances are items we hope to have in place pre-retirement. Especially since the cost and the ability to become insured becomes incredibly difficult, the older one gets. However, maintaining these policies, understanding them, and having assistance once it comes to time to draw on the benefits is quite another story.

6. Estate and Multigenerational Planning - It makes sense for clients to manage their estate planning even after retirement and until the end of their lives. It’s the best way to ensure that their wealth is passed on to the next generation in the most efficient way possible. This is partly why we manage retirement income so close (account titling, beneficiaries, and estate documents). We also encourage families to document assets and have family conversations about their values and intentions for how they wish their wealth to be passed on. Many planners can help to structure and facilitate these kinds of conversations.

7. Planning for Aging - For many clients just entering retirement, one of their greatest challenges is how to help their now elderly parents manage the aging process. Like how to navigate the health care system? How to get the best care? How to determine the best place to live as they age? How best to pay for their care, especially if parents haven’t saved well enough for their retirement? How to avoid digging into your own retirement pockets to pay for your parents’ care? How to find the best resources in the community? And what questions to ask (since this is likely foreign territory for most)?

Since humans are living longer lives, there will likely be an increased need and/or desire to plan. In an emergency, it could be difficult to make a decision uninformed. A planner can help you create a contingency plan for potential future health changes.

While it seems like the majority of materials, time, and energy of the financial planning world focuses on planning to reach retirement, there is so much still to do post-retirement. Perhaps as much OR MORE as there is pre-retirement. Having the help of a planner in post-retirement is likely something you might not realize you needed, but something you’ll certainly be glad you had.

Sandra Adams, CFP®, is a Partner and CERTIFIED FINANCIAL PLANNER™ professional at Center for Financial Planning, Inc.® and holds a CeFT™ designation. She specializes in Elder Care Financial Planning and serves as a trusted source for national publications, including The Wall Street Journal, Research Magazine, and Journal of Financial Planning.

The foregoing information has been obtained from sources considered to be reliable, but we do not guarantee that it is accurate or complete, it is not a statement of all available data necessary for making an investment decision, and it does not constitute a recommendation. Any opinions are those of Sandra D. Adams and not necessarily those of Raymond James.

Securities offered through Raymond James Financial Services, Inc. Member FINRA/SIPC. Investment advisory services offered through Center for Financial Planning, Inc. Center for Financial Planning, Inc.® is not a registered broker/dealer and is independent of Raymond James Financial Services.